Pitching investors is a lot like speed dating.
You walk in, you have a short window, and everyone across the table is quietly deciding one thing: do I believe this person, and do I want to be in business with them? The deck matters. The model matters. But the person in the chair matters most.
At Belae Brands and then at Innovative Brands, we pitched constantly. Investors like SAC Capital Advisors. Banks like Credit Suisse and Scotiabank. Mezzanine lenders like Cerberus Capital Management. Different rooms, different suits, and the same basic dynamic every time. They were not there to be entertained. They were there to find out whether our story held up.
Here is what I remember most.
The eight hour session
The most memorable one was with SAC Capital Advisors, before its 2013 fall. Two of their associates sat down with us and went through our financial model line by line. Then they quizzed me on it. Why this number? Why this growth rate? Why do you think you can build these brands?
It lasted eight hours. It was grueling. They were tough negotiators, especially on ownership percentage, and they were relentless.
What stays with me is that they were tireless. They kept coming back to the same questions from different angles, looking for the place where the story would crack. If there was a soft spot in the model, they were going to find it.
That is what serious money does. It tests the story before it trusts it.
The question they asked every single time
In every single pitch, someone asked the same thing in some form: can you actually grow these brands?
We were buying brands that big companies had decided to sell. So the follow up was always about innovation. Is there enough newness left in these categories to drive growth beyond what the brand does today?
Our answer was that the brands were on autopilot. The companies that owned them had stopped pushing for innovation. Nobody was bringing new products, new scents, new formats. We said there was growth sitting there for the taking, and we backed it up with my background.
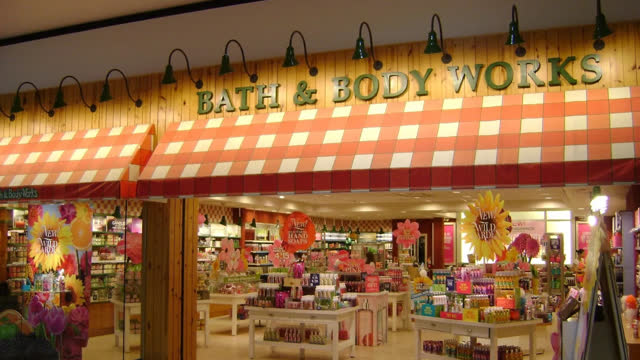
At Bath & Body Works and at Dial, I had spent years introducing newness. New products, new lines, new ways to give a shopper a reason to come back. That was not theory. It was something I had done, and I could talk through how it worked.
That matters, because an investor can hear a hundred people say “we will innovate.” Very few can show they already have.
Age did not matter. Experience did.
In those rooms, age did not matter. Experience did. What they cared about was whether I had done it before.
I had run a vertically integrated business at both Bath & Body Works and Dial. That gave me something I could do in the room: I could recite where we could produce the items, at what cost, and show that the numbers worked. We had suppliers lined up. We had some early market research from fragrance houses that helped lend credibility to the story.
None of that was fancy. It was facts, and facts travel well. When someone across the table asks “how do you know you can make this at that cost,” the best possible answer is a name, a number, and a conversation you have already had.
Have your facts. Do your homework.
If I could give a first time founder one rule for an investor meeting, it would be this one.
Have your facts. Do your homework.
Know your costs. Know your suppliers. Know your customer. Know where your numbers come from and what happens to them when one assumption moves. You do not need to know everything, but you need to know what you know and what you do not.
And when you do not know, say so. Then tell them how you are going to find out, and follow up. “I do not have that number today. Here is how we will get it, and I will send it to you by Thursday.” That answer builds trust. A confident guess that falls apart later does not.
You are interviewing them, and they are interviewing you
One more thing took me a while to understand. These meetings are an interview for the investor.
They are not only judging whether your business is good. They are deciding whether they want to spend years working with you, through good quarters and bad ones. They are listening for how you handle a hard question, how you respond when you do not know, and whether you stay steady when someone pushes back.
That is why the story has to be believable, and why you have to believe it. Not hype. Not polish. A clear, honest account of what you are going to do, why you can do it, and what you will do when something goes wrong.
Speed dating, right? A short time, a lot of signals, and one question running underneath all of it. Do I trust you?
You only need one or two
Here is the part nobody tells you. We took a lot of meetings, and we only needed one or two partners to get the deals done.
That changes how you should think about the whole process. Most rooms will not end in a yes, and that is normal. It is not a verdict on you or the business. You are not trying to win every meeting. You are trying to find the one or two people who believe the story and will back you.
So the goal is less about success and more about surviving it and keeping your sanity. Take the hard questions. Learn from the ones you stumbled on. Go back in the next day with a better answer. A long run of “not for us” is part of the job. I wrote about a stretch like that in After Hours: The Art of Failing, four deals that fell through before the fifth one closed.
What I would tell you before your first one
Do the work before you walk in. Practice the hard questions out loud. Bring numbers you can defend and a name behind every assumption. Be honest about what you do not know yet, and be ready with the plan to find out.
Expect tireless people. Expect them to circle back. Treat it as a compliment. They would not spend eight hours on a deal they did not take seriously. And expect plenty of nos. You only need one or two yeses.
And remember that the person across the table is deciding whether they believe you. Give them reasons to.
If you want to know what came after one of those closings, I wrote about it in After Hours: Now What?.
If you are getting ready for an investor meeting and want a second set of eyes on your story, grab 15 minutes with me and tell me what you are walking in with.